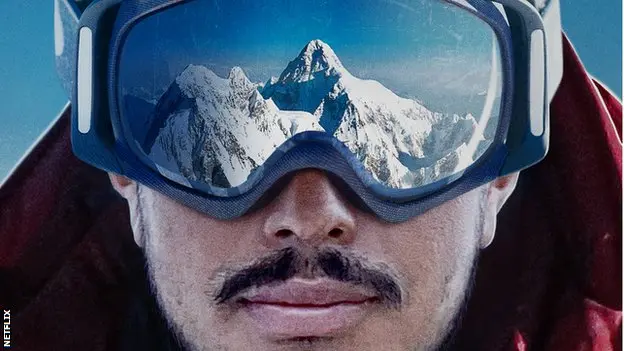
It is common for financial professionals to go through challenging times. I know that in my career I have had struggles with staying focused and have a clear direction. I always felt like there was a better way to do business. After becoming fascinated with documentaries of people doing extraordinary things, there was only one that really stood out to me. His name is Nimsdai Purji. He is a Nepalese mountain climber who set out to break the record for climbing the world’s 14th highest mountains which previously took 16 years by Reinhold Messner from 1970 to 1986. Purji was able to accomplish this feat in less than 7 months.

The Netflix documentary is “Nothing is Impossible,” and it is a must watch. The purpose of me telling you about this was to tell you something else. More people are getting to the top of Mount Everest than ever before. There are many reasons for these numbers. The first reason is that the more climbers get to the top, the more experienced climbers that there are to help others get to the top. This is the same for financial services. The more advisors that have success, the more experts there are to teach others. The second reason would be climbers have found the easiest routes. After years of trying diverse ways to the top, Climbers can now map out the easiest routes. This is the same in financial services. Over time, we tend to find the easiest routes to success. Copy what someone else is doing and have the same success. This only makes sense right? The problem with these statements is that we all have different educational backgrounds, and different skill sets. Copying the world’s best salesperson is not going to make me exactly like them. I may pick up the language. I may pick up the ways to say certain things, but I will never be that person. To think this model is replicable will only lead to failure. This is one of the main problems in any sales industry. We are all different, so it makes it extremely difficult to copy what someone else is doing. I have seen this in our industry numerous times. The top salesperson teaches the class, and very few can copy what they do and get the same results. If this were true, then I should be able to take Tiger Woods’ Golf clubs and coach and break course records. My game may improve drastically, but I will never be as good as Tiger Woods. We must create a system that can be replicable, and experts to surround ourselves with. This is how you climb Everest.
Climbing Everest is one thing, but our goal is not to climb the mountain. The goal is to climb the mountain and come back down. The interesting stat about the death rate at Everest is that 80% of the deaths happen on the way down. Around 80% of all business owners fail as well, and I feel there is a direct relationship between these numbers. I call it dedication and preparation. I really do not think that anyone that climbs Everest or opens a business, plans to fail. Everyone is dedicated to the success of their journey. I do feel the failure rate is due to the lack of preparation. You must know what is ahead of you to be prepared but also plan for what you do not know. Our jobs are to help clients reach their maximum potential while reducing risk. Their job is to execute their skillset. Together we want to maximize their potential and help reduce risks for the client.
This playbook is going to show you how to laser in on Focus, Dedication, Preparation, and how to surround yourself with experts so that you can climb your Everest.

Forward
Chapter 1: Problems With Financial Representatives
a. Go-it-alone
Too many times, in my career I have heard the phrase “eagles soar alone, buzzards go together.” I do believe this to be true in some cases. Our industry is not one of these instances. To be a top producer, you will need a team of people that do the things that you do not do well. Early in my career I was paired with a veteran producer who just so happened to be the top producer in our Dallas, Texas agency. He truly was an eagle, or so I thought. I did learn so many things from this advisor. Staying busy with what you can control was the main thing. You cannot make people buy. You cannot control their personal life. You cannot make them like you. All you can control is how many people that you can get in front of. This was my model for years. However, I do not think my preparation was as good as it could be. My message was not easy to duplicate, and my results were up and down. I will show you how to beat the “go it alone” narrative as we progress through the upcoming chapters, so that you can build your team and get to the top.
b. Education
Working in the business owner space is not an easy task. You really need to know how a business operates. Justin Waller is a famous social media personality, and a multi-millionaire once said: “if you are going to be in the construction business, you better understand property and casualty insurance.” Notice he did not say: “you better understand investments or banking.” I am not taking a jab at those industries, but most business that we see fail is because of their property and casualty premiums and how they pay for these premiums. If you are going to work in the business owner space, you must learn about other aspects of financial services. You do not have to be the experts in these other specialties, but you need to know as much as your client if not more. Educate, educate, educate. Learning other pieces of the financial services industry has changed my career, and it will do the same for you.
c. Focus
Create a clear path on what you are selling. When I am asked “what I do for work,” my answer every time is: “I do business financial planning.” This is what I want to do every day, and I spend all my time focusing on doing this. From business cards to webpages, my focus is noticeably clear on what I am doing. My goal with a new client is to sell them on the fact that I need all their information. I know that this step alone is getting a commitment from the client, and from here I can uncover all the issues and help my client in the best way. I do talk about products, only concepts of efficiency and reducing risk to redirect loss of capital.
d. Jack of All Trades
Our industry has created a lot of “jack of all trades” advisors. If someone asks me about a Medicare solution, my answer is “I know someone that specializes in Medicare, let me introduce you to them. I work in business planning and consulting.” If someone asks me about home and auto insurance, my answer is “I know someone that specialize in the person lines insurance that is incredibly good at what they do. Let me introduce you to them.” You get the point. You will never play at the level you want to play at until you take on this mentality. Tom Brady does not kick the field goals. He does not run the ball. He does not catch the passes. He throws touchdowns and wins Super Bowls. Be the quarterback….. they get paid the most.
Chapter 2: Solutions
a. Specific Direction
The entire purpose of the 400k playbook is to teach someone how to work in the business owner space at an elevated level. There are extremely specific reasons that we choose this path, and specific ways on how to execute with specific intent on what we are trying to accomplish.
b. Playbook
We know everyone cannot replicate the eagle; however, we can replicate the playbook. This book will give you a step-by-step guide along with marketing materials to help you build your career.
c. Team
It will take a team of people to accomplish working with business owners at an elevated level. The jack of all trades model will not work. Our team consists of financial advisors, insurance agents, group benefits advisors, property and casualty experts, home office attorney’s and CPAs, and of course the quarterback. If you add up our entire team, there are probably over 500 people supporting each client. If you were a business owner, do you want a lone eagle helping you? How about you represent your teams of eagles that have specialties that they soar in, and you are the person that brings it all together with the comprehensive plan? This is how we approach every client and win at the highest closing rates in the industry.
d. Partners
You will need many partners to be successful. We have partnered with 2 major insurance companies that provide products and support at the highest level. These companies need advanced planning teams with great attorneys and accountants. You will need specialists that do the things that you cannot do. You will need a commercial property and casualty team. You will need a retirement planning specialist. You will need a disability insurance specialist. You will need a life insurance specialist. You cannot do this alone. If you attempt this then you will fail.
e. Execution
It is down to us as individuals now. We have a plan, a model, a team. The only thing left to do is execute. Imagine yourself 22 years old. If I were a recruiter and told you that if you can get 15 to 20 business owners to fill out a questionnaire, then you can expect to make 400k a year, how fast would you join our team? You will sign up tomorrow. Guess what? We have this opportunity!
Chapter 3: The Sales industry
If you want to be successful in any sales industry, there are a few things that you need to look for to make this happen.
a. Clear Model
Our model is business financial planning. Only business financial planning. We use Financial Four Square as our planning software, and every client’s information goes on this model. We have a team of specialists to do the things that we are not experts in, and we work as a single unit.
b. Easy to communicate.
Your clients must be able to understand exactly what you are selling. I am selling business financial planning. “I have a model that we created because it did not exist before now. We can use this model to find mistakes that could cripple your business. If we can fix these mistakes and put capital back into your business or personal pocket, then would you want to see what that looks like?”
c. High Demand
You do not want to sell a product or service that is on every street corner. There are 6.9 million business owners in America. There are only a handful of people that do exactly what we are doing.
e. Support
You are going to need a support staff. If you do not have one, use mine.
f. Replicate
Can you do the same thing over and over? We do build custom plans, but our presentation is the same every time.
Chapter 4: The Model
a. Image
Represent yourself as a business financial consultant. Look the part. Dress professional. Have nice marketing material, which we have created. Create a brand so that people know what you do when they see you and your name.
b. Current position
Know exactly where you are in your career. Know what you can and cannot do. Let people do the things that you cannot do. Do not try to reinvent the wheel.
c. Solutions
We have spent tons of money building the Financial Four Square software. It has taken decades to create, and it is only getting better. Learn it and use it. Surround yourself with teammates who understand the process. Let them make you money. Be the quarterback.
Chapter 5: Market Overview
a. Number of business owners
6.9 million business owners.
b. Amount of revenue generated.
5.9 trillion dollars generated in revenue.
c. Competitors
Less than 10 business planning firms in the country today.
Chapter 6: Failure Rate
a. 80% of all business fail by the 10th year
b. 20% of businesses fail in the first 12 months
c. By the 5th year 50% of businesses have failed.
I am 99% sure that most businesses do not set out to fail. Most of the time, business owners even hang on a little too long. So, the dedication is usually there. I also believe that must business owners are skilled at the particular craft. They could be a dentist, a plumber, a hair stylist, or anything else. They may not be very good at bookkeeping, or employee benefits, or taxes. If this is the case, then how do business owners make decisions? Who do they turn too? They turn to their CPA or their attorney possibly. CPA’s and attorneys are good with taxes and law, but they typically are not good with insurance products, and this is ok. Insurance agents are not typically good with taxes and law. It is not what they are trained to do. I once had a CPA tell me that he doesn’t need and insurance license to give insurance advice, because legally he is exempt from being licensed. I agreed with him, but he is not exempt from a lawsuit from giving wrong advice. The moral to the story is, stay in your lane. This is exactly what is wrong with the financial services industry. There is bad advice being given from advisors who are not qualified in other specialties. Do what you are an expert in and surround yourself with the people that you need to do the things that you cannot and aren’t good at. It takes a team working together to really outperform your competition. My team consist of accountants, legal advisors, insurance agents, and investment advisors. Inside of this model, I have a team of specialists. Tax specialists, Property & Casualty Specialists, Life insurance Specialists, Disability Insurance Specialists, Retirement Plan Specialists, Health Insurance Specialists, Legal Advisors, Investment Advisors, and myself “the quarterback.” Someone has to make sure that all of these specialties are working in the best interest of the client, and products become part of an overall strategy. This is where the Financial Four Square software comes in.
Chapter 7: Competition
a. Industry specifics and Issues:
There are almost 6000 insurance companies in the United States. How on earth can someone that does not work in the insurance industry give product or coverage advice on an industry of this size without being immersed in it every day? It is impossible. This is why there are specialists. There are almost 6000 stocks on the stock exchange. Why would one ask your neighbor about what stocks they are buying after he or she works 8 hours at their full-time job? This process is not even rational, but it is what we do in today’s world. Our country is full of armchair quarterbacks. Everyone has the answer in hindsight. Our team has the answers today because we take a macroeconomic approach, and then we take microeconomic specialists to fine tune one’s business.
Chapter 8: Multiple sources of Income
If a business planner specialist wants to be successful in this business, they are going to need multiple sources of income. Notice that I did not say they need to sell multiple products. What I mean by this is that when I am working with a client and my team has determined that the client will need employee benefits, my employee benefit specialist with do what they do, and I will in return get a piece of the commission if I am properly licensed. I will focus on what I do best, and that will be the bulk of my pay. I will not “refer” business to someone to help my client and not be compensated and you should not either. There are 4 major sources of income in business planning. 1 is life insurance. 2 is disability insurance. 3 is property and casualty insurance. 4 is employee benefits and retirement planning. “If you are the rain maker, make it rain.” I must say again, one must be licensed to receive any commissions. Check with each states law to confirm.
Chapter 9: Team Model
Creating a team in this industry is not as simple as one might think. For example, if I want a really good property and casualty agent on my team, where would I look to find one? In the business owner space, I would not go to a Farmer’s or a State Farm agent. Not to pick on these two, but I need an independent agent that specializes in commercial insurance only. If the p&c agent tells you that they sell personal lines as well, then they are not the right person for this job. Partner with someone that only sells commercial insurance and has a team of their own. Stay away from the big box shops. It can be difficult to share work. After you identify the right p&c agent, we now have to train them on business financial planning. This is the hard part. Because their only focus in on coverage and price, we have to teach them financial strategy. Thay have to be on board with the concepts and strategies that one could be using. Example: If part of our strategy is to raise deductibles and self-insure some risk to lower premiums, then a business owner must have that savings set aside to pay a claim for their portion of the risk. I have had property and casualty advisors tell me they use this strategy on a regular basis. My question to them is “where did you put the money.” There usually is no answer to this. My point is this, they have to be trained. This is the same for your other specialists.
Brent White is the CEO of BOSS Financial Group. If you are looking to take your career to a new level, then feel free to reach out on the website: